Ipswich, QLD
Construction Loans Ipswich
We arrange and manage construction finance for Ipswich house-and-land and knockdown-rebuild projects, coordinating each drawdown with your builder so the payments land when they are due.
A construction loan does not work like a normal home loan and the differences catch people out. Money is released in stages, interest starts small and grows, and the valuation that matters most is done on a house that does not exist yet. We handle that machinery so you can deal with the build.
How We Manage Your Build Finance
We structure the loan, coordinate the progress payments and valuations with your builder and the lender, and convert the loan to principal and interest once the build is finished.
The work is mostly in the timing. Builders invoice on stage completion, lenders release money only after an inspection, and the gap between those two events is where projects stall. We sit between them and keep it moving.
You might be holding a house-and-land package from a display village, a block you already own plus a builder's quote, or a plan to knock down and rebuild on a site you have lived in for years. The finance differs in each case.
What Happens After You Contact Us
-
First conversation, about 20 minutes.
What you are building, where, with whom, and what stage the contract is at. Free.
-
Structure and capacity.
We come back with a build finance structure, a drawdown plan and where the scheme timing sits.
-
Application.
We lodge with a lender that handles construction well. Not all of them do it equally.
-
Staged drawdowns.
We coordinate each payment with your builder and the lender through the build.
-
Completion.
Final valuation, final payment, conversion to principal and interest.
What to have ready
Have your fixed-price contract, council-approved plans, your builder\'s licence details and the insurance certificates ready. If you do not have all of them yet, we can start without them.
What Happens When You Get in Touch
Tell us where you are up to and we work out what you can borrow, which lenders suit your situation and what the next step looks like. If the answer is that you are better off waiting, we tell you that too.
Our first conversation costs you nothing. On standard residential loans the lender pays us a commission when your loan settles, so there is no fee to you. If an exception ever applied, it would be in writing in our Credit Guide before you committed to anything.
Ask about construction loans
Tell us where you are up to and we will come back the same day with what you can borrow, which schemes you qualify for and what deposit you would need. No cost, and no obligation to go ahead.
How We Manage Your Progress Payments
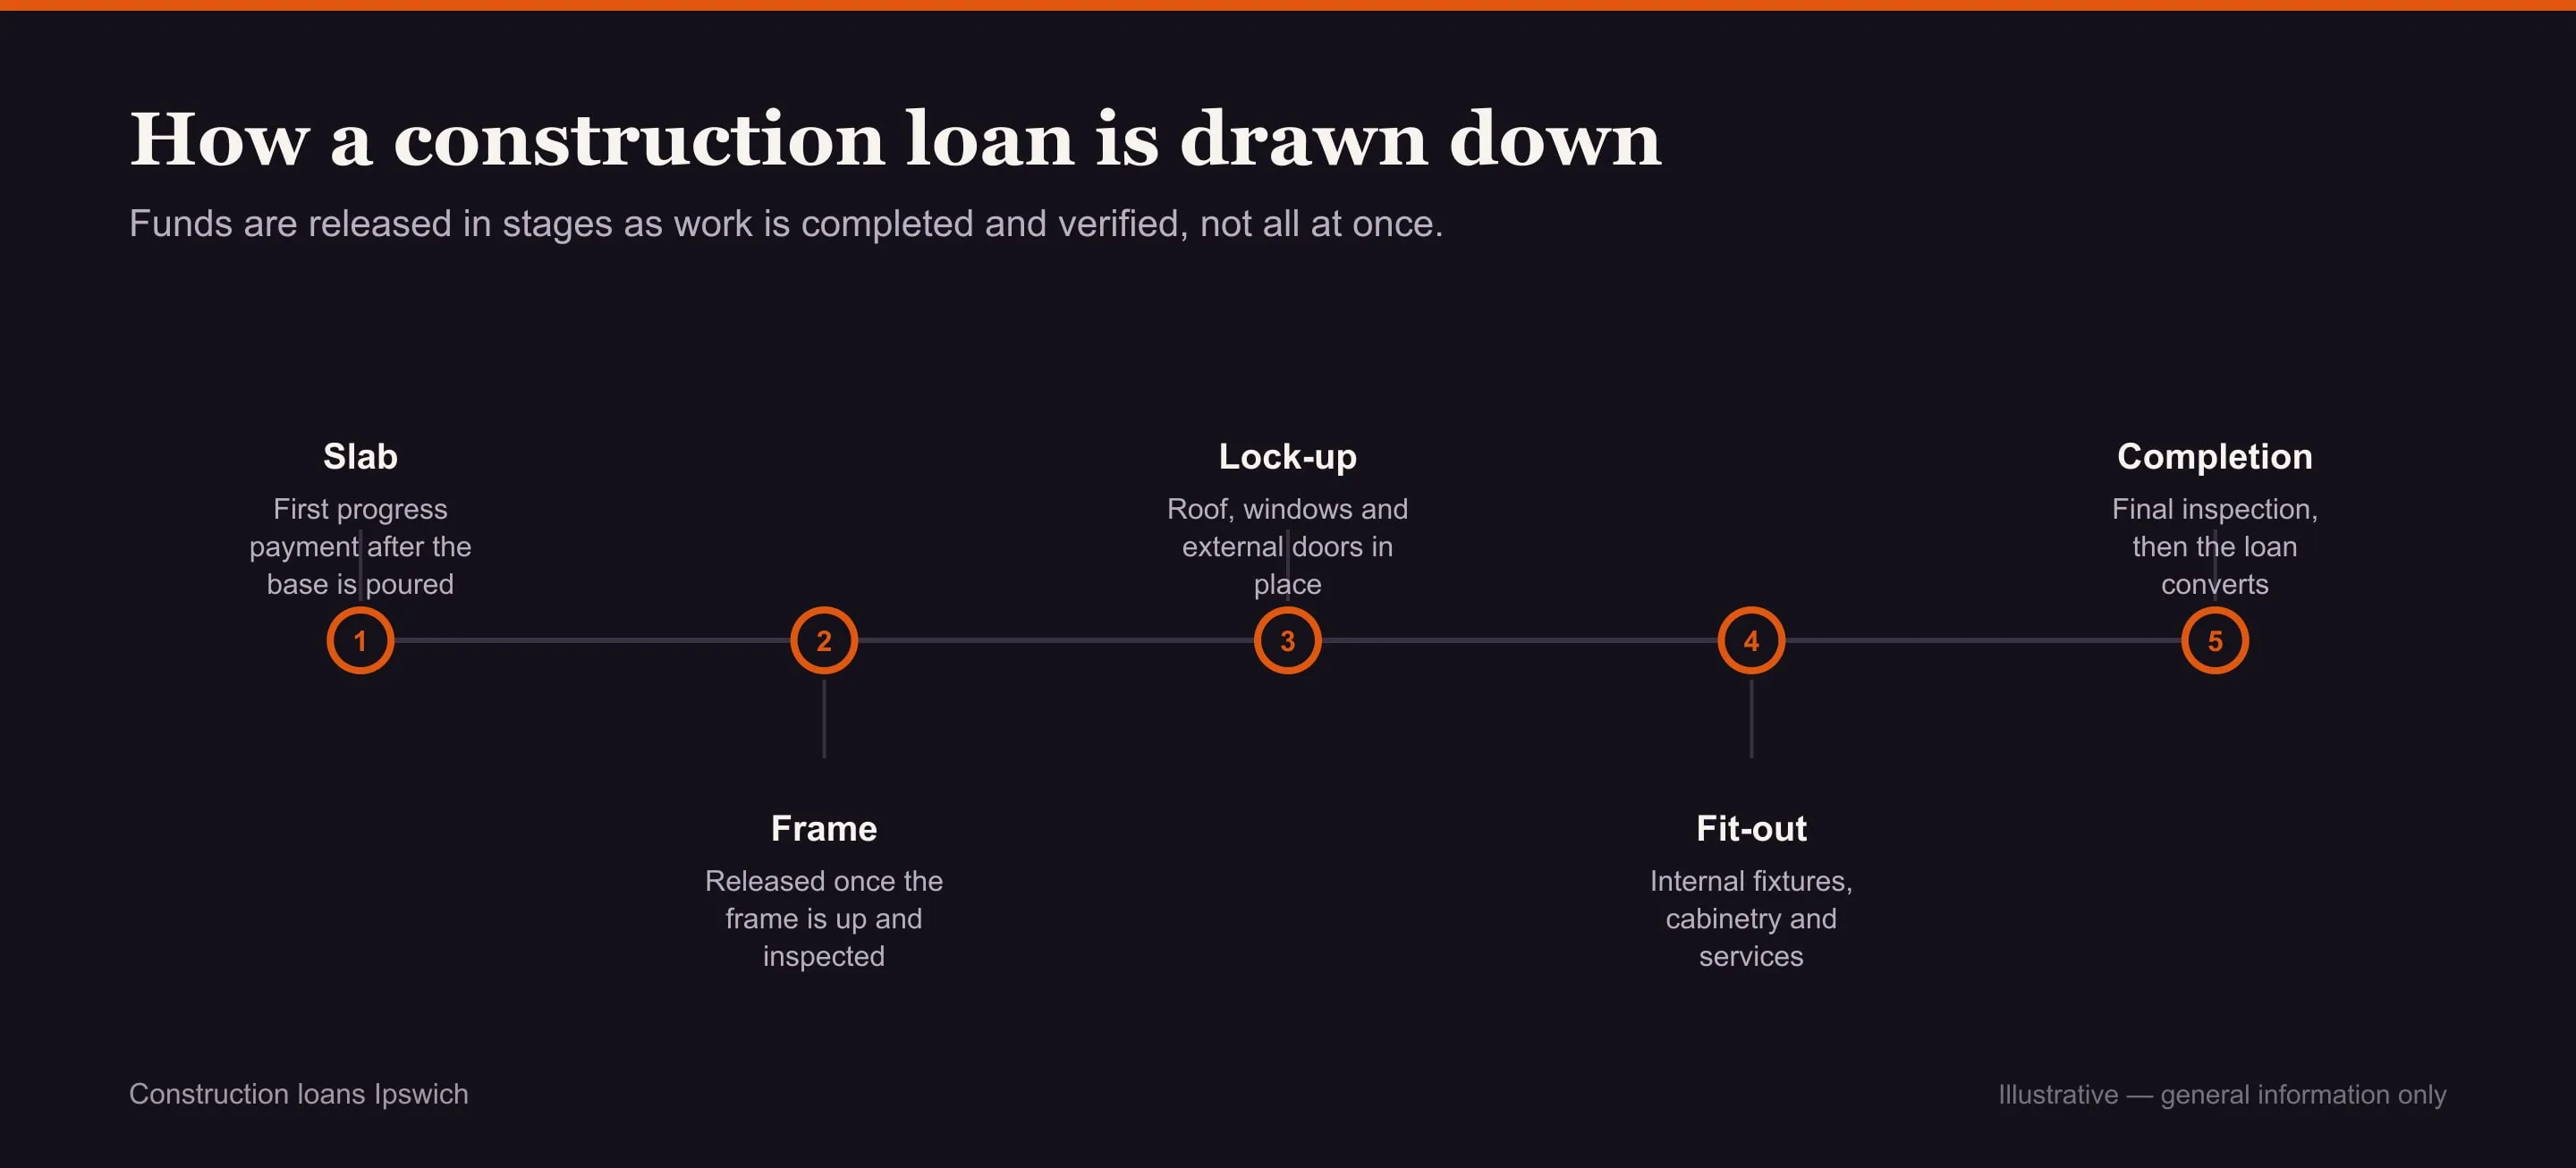
Your loan is not handed over as a lump sum. It is released in stages as the build progresses: deposit, slab, frame, lock-up, fixing and completion.
You are charged interest only on what has actually been drawn, so your first repayment after the slab pour is small, and it grows with each stage until the build finishes. At completion the loan converts to principal and interest and behaves like a normal mortgage. We schedule the drawdowns so you are not paying interest on money the builder does not need yet.
Each stage requires the lender to inspect and approve before releasing funds, and there is generally a fee for each drawdown and inspection. Those add up, so we factor them into the plan rather than letting them appear as a surprise.
The final payment is the one to watch. It is not released until a completion valuation confirms the finished house matches the approved plans. If the builder has varied something without approval, that payment stalls. That is why we ask to see variations as they happen rather than at the end.
Valuation Risk in New Estates: What We Check
The lender values your build "as if complete". It works out what the finished house will be worth and lends against that figure, not against what you agreed to pay.
If that valuation comes in under your contract price, the shortfall comes out of your pocket as extra deposit. In a fast-moving estate with limited settled sales to compare against, valuers have thin evidence to work with and tend toward caution. That is a live risk in Ipswich right now, not a theoretical one.
So before you sign, we look at what has actually settled in that specific estate. Not what is listed, what has settled. Then we flag it if the numbers look stretched. It is a much cheaper conversation to have before you commit than after the valuation comes back.
Building in the Growth Estates
Ripley is the fastest-growing suburb in Queensland, adding 649 new dwellings and 2,024 residents across 2024 and 2025 alone, a 15.4% increase in a single year. Spring Mountain is close behind with 523 dwellings and 1,597 new residents over the same period.
That pace is why so much of Ipswich is under construction, and it is also why valuations need watching. A large number of near-identical homes settling in the same estate at the same time gives a valuer plenty of comparables. That cuts both ways. If the estate softens, your valuation softens with it.
Building in Ipswich also unlocks the $30,000 first home owner grant and the nil transfer duty concession, which do not apply to established purchases. Contract timing decides whether you capture them, so if you are building your first home we sequence the build contract around the scheme rules. The detail on those schemes sits on our first home buyer loans page.
Which Build Path Suits You
A house-and-land package is usually two contracts: one for the land, one for the build. The land settles first and construction starts after. It is the more common path across the Ipswich growth estates and the simpler one to finance.
A turnkey package is a single contract with the builder delivering a finished home, driveway, landscaping and all. It costs more upfront but there is far less for you to organise and fewer opportunities for cost creep.
A knockdown rebuild uses your existing property as security and is common in the older established Ipswich suburbs where the land is worth more than the house on it. The finance is more involved because you need somewhere to live during the build and the lender needs the demolition handled properly.
Lenders almost always want a fixed-price building contract with a licensed Ipswich builder. Cost-plus arrangements are harder to finance and usually come with a lower maximum loan-to-value ratio. Owner-builder finance is materially restricted. A minority of lenders will consider it, at a reduced LVR, and it is not a routine path. If that is what you are planning, tell us early because it narrows the field considerably.
How We Protect You If a Builder Fails
Builder insolvency is the risk nobody wants to plan for and everybody should. It has hit Queensland projects hard in recent years, and Ipswich estates were not spared.
Check your builder holds a current QBCC licence for the class of work. The Queensland Building and Construction Commission licenses residential building work here, and the licence is searchable. Confirm the Queensland Home Warranty Scheme cover is in place, and check contract works insurance is active for the duration.
We ask for those documents at the application stage anyway, because the lender wants them. What we are really doing is making sure you have looked at them before you sign, not after.
Structuring a realistic contingency into the loan also matters. Builds run over, variations happen, and having a buffer inside the facility beats scrambling for cash at the fixing stage.
Construction Loans Ipswich Questions
What documents do you need to get started?
Ideally your fixed-price building contract, the council-approved plans, your builder's QBCC licence details and their insurance certificates, plus the usual income and deposit evidence.
You do not need all of that to have the first conversation. If you have a quote and a block in mind, that is enough for us to tell you whether the numbers work.
Do you coordinate the drawdowns with my builder?
Yes. That is a large part of what we do on a construction file. Your builder invoices on stage completion, we submit it to the lender, the lender inspects, and the funds are released.
We chase the inspections and follow up when a payment sits. Builders have a low tolerance for slow payments and it is the fastest way for a good relationship to sour, so we treat it as our job rather than yours.
Why do I only pay interest on the money that has been drawn?
Because you have only borrowed that much so far. If your total facility is approved but only the land and slab payments have been released, interest is charged on that released amount alone.
It means your repayments start small and step up with each stage, then convert to principal and interest at completion. Budget for that. The repayment at lock-up is considerably higher than the one after the slab.
What if the valuation comes in under my contract price?
You cover the difference. The lender calculates its lending against the valuation, not against what you agreed to pay, so a shortfall lands on your deposit.
This is why we look at settled sales in your specific estate before you sign rather than after. If the gap is large there are options: a different lender, a second valuation, or renegotiating. All of them are easier before you are contractually committed.
Can I still get the first home owner grant if I am building?
Building is generally the only way to get it. The Queensland grant applies to new homes under $750,000 including land, and established properties do not qualify.
Contract dates decide eligibility, so the timing of when you sign matters. The full detail sits on our first home buyer loans page and we check your specific situation against the current rules before you commit.
Talk to a Mortgage Broker in Ipswich
Tell us where you are up to and we work out what you can borrow, which lenders suit your situation and what the next step looks like. If the answer is that you are better off waiting, we tell you that too.
Where We Arrange Construction Loans
We work across the whole of Ipswich and the western corridor, from the established streets closer in to the new estates on the edge. Most of what we do happens by phone and email, so where you are inside that footprint does not change how we work or what it costs you.
Mortgage Broker Ipswich
Ipswich, QLD 4305
Monday to Friday, 9am to 5pm
ABN 38 361 529 668